
Reel Risk and Real Risk
Insurance lessons from the screen and from the decisions professionals make every day.
Reel Risk uses movies and television to ask what a policy might do when the story turns into a claim. We follow the facts, examine the coverage questions, and see where the outcome may be less obvious than it first appears.
Real Risk looks at the choices facing insurance professionals and agencies, from using AI responsibly to evaluating technical knowledge, developing people, and understanding the consequences of a coverage decision.
We invite you to explore the articles below. Some begin with a scene; others begin with a challenge in the industry. All invite a closer look at how insurance works.
Did Nakatomi's Builders Risk Survive the Christmas Party?
Nakatomi Plaza was occupied, but construction was still underway. After the Christmas Eve mayhem, would Builders Risk cover the damage? The answer turns on a policy provision many readers may remember differently.
AI Gave the Agent a Business Income Limit
AI can calculate a Business Income limit from the information it receives. But what happens when a critical fact about the insured was never supplied? Two fictional claims reveal why the investigation, the policy and the insured’s decision still matter.
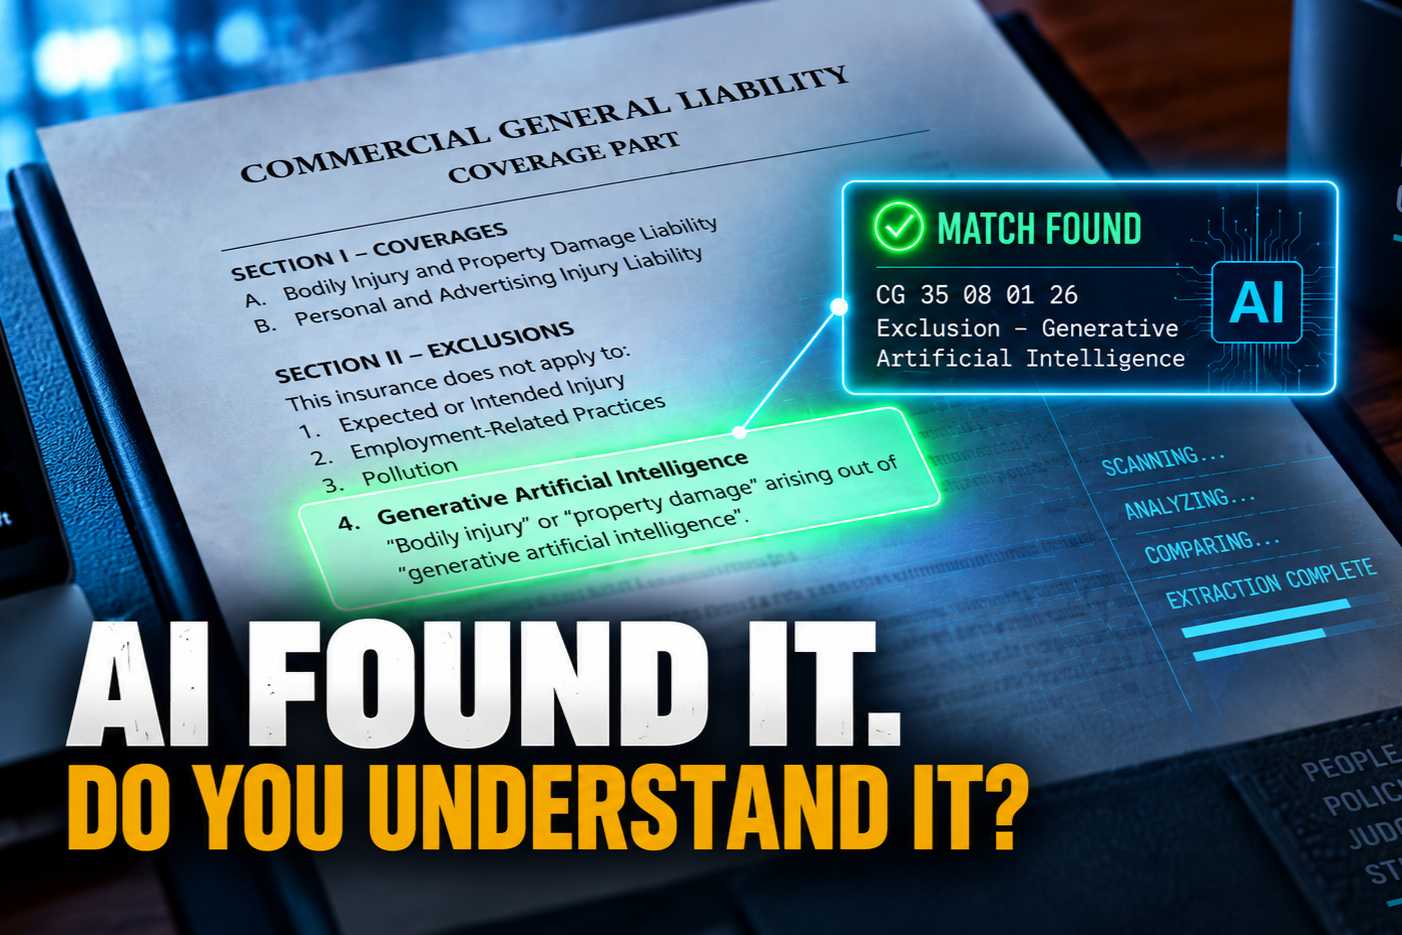
AI Found It. Do You Understand It?
AI can compare policies, identify changes and flag potential coverage issues. But as AI also creates new exposures and policy exclusions, technical insurance knowledge may matter more than ever. Here’s what we heard at ASNOA Connect 2026.
When Your Product Bites Back: The Isla Nublar Claim File
When InGen's dinosaurs escape, the resulting catastrophe creates far more than a products-liability claim. Follow the policy language from the CGL aggregate question into the connected people, property, auto, cyber and time-element claim files.

Reel Risk: The Overlook Claim File
Would Jack Torrance’s death be compensable under Workers Compensation? Enter the Overlook claim file for a Reel Risk analysis of Part One, Employers Liability, and the hotel’s potential CGL exposure.

The Résumé Says “Experienced.” But What Does the Insurance Candidate Actually Know?
A résumé can document experience, production, and responsibility. It cannot show whether a Producer or Account Manager can identify coverage concerns, protect an inherited book, or apply technical insurance knowledge when it matters
Does “Any Auto” Mean Any Auto? A Business Auto Coverage Analysis
Does Symbol 1, “Any Auto,” automatically create coverage? This Reel Risk analysis follows the policy language from covered auto through the insurer’s duty to defend.